Early Loan Settlement in Saudi Arabia: The SAMA Fee Cap, Worked Examples, and When It Pays
TL;DR
SAMA caps the early settlement fee on a Saudi personal loan at the profit of the three months after you pay, on the declining balance. Here is the rule (Article 84), the regulator's own worked example, and the point in a loan's life where the saving drops to zero.
Table of Contents
Early loan settlement in Saudi Arabia: the short answer
Run your own loan through the Cubbbix Early Loan Settlement Calculator before you ask the bank for its quote, and check the bank's figures line by line against yours.
Settling a personal loan early in Saudi Arabia costs your remaining balance plus a fee, and the Saudi Central Bank (SAMA) caps that fee in writing. The cap is the profit, called the term cost, of the three months after your payment, on the declining balance of your own repayment schedule. Profit for every month after those three is cancelled in full.
This guide sets out the rule as SAMA published it, walks through the regulator's own worked example, and shows where the saving is large, where it shrinks to zero, and what to request from your bank before you pay.
Figure 1: Your repayment schedule holds every number in this guide: the balance after each payment and the profit charged monthly.
The rule SAMA wrote for early payment
Article 84 of the Implementing Regulation of the Finance Companies Control Law gives the borrower the right to pay off the rest of the financing amount early, at any time. The borrower does not pay the term cost of the remaining period. The finance company may be compensated for two things: the cost of re-investment, capped at the term cost of the following three months of payments on the declining balance, and payments it made to a third party under the finance agreement where those expenses are irrecoverable, for the remaining term.
The same three-month cap repeats across SAMA's rulebook: Article 11 of the finance lease regulation for early ownership of a leased asset, Article 69 of the consumer microfinance rules for microloans. Saudi Finance Company restates it in its published customer terms: on full early repayment it takes the remaining principal plus a profit equal to the following three months, on the declining balance method.
Two rights sit next to the fee rule. A lender must accept a partial prepayment equal to one full installment or a multiple of it. Under SAMA's conduct rules, the lender must also hand you a detailed amortization schedule free of charge within one business day when you ask, and notify you of the early payment fees in writing within 10 business days.
One number causes steady confusion. The 1% cap in Article 83 limits administrative fees at the start of a contract: 1% of the financing amount or SAR 5,000, whichever is less. Early payment compensation has its own cap, the three-month term cost rule above. Press coverage of a 2026 SAMA update described early repayment charges of around 1% of the outstanding balance as past market practice. The cap in the regulation is the three months of term cost.
How the fee comes off your schedule
Saudi lenders spread the term cost across installments on the declining balance. Each month, the profit part of your installment is the rate applied to the balance at the start of that month; the rest pays down principal. The profit slice is widest early in the loan and narrows as the balance falls.
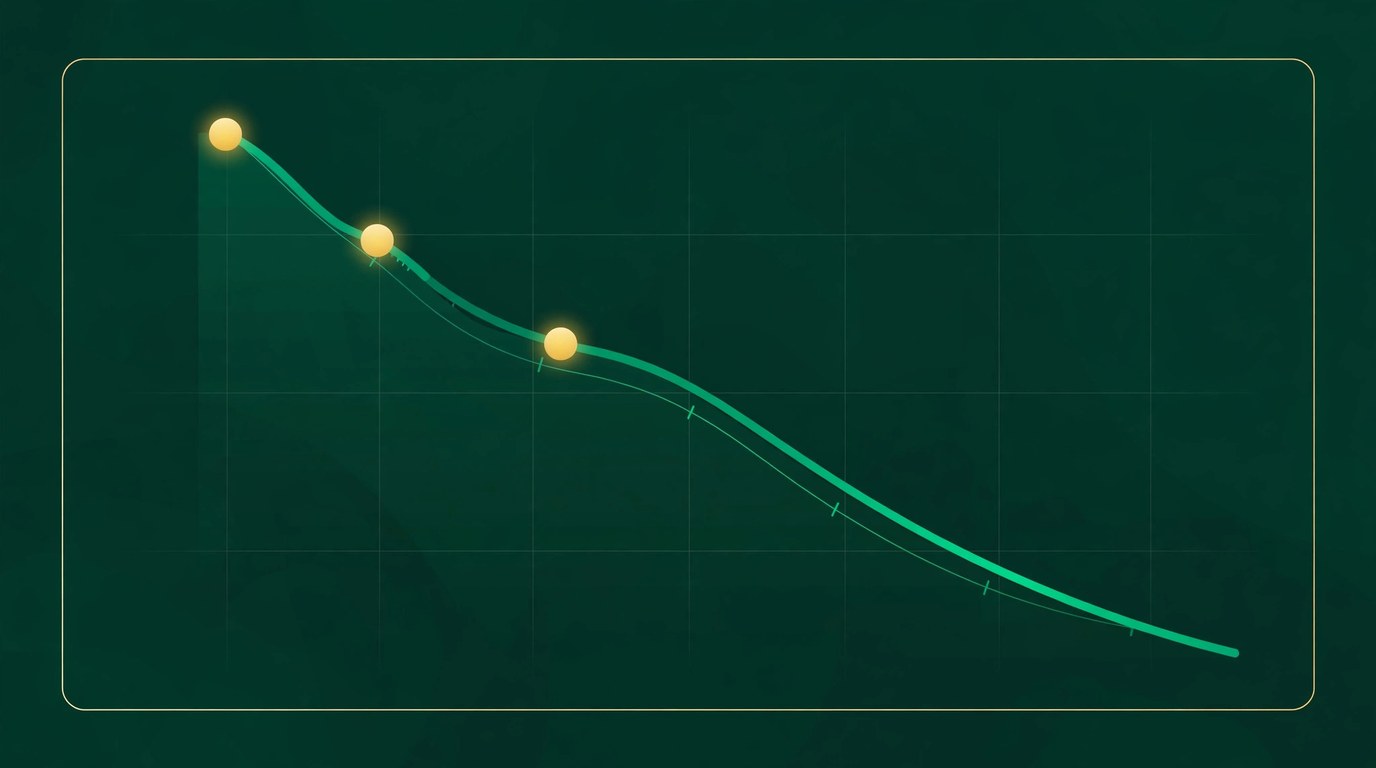
Figure 2: The fee is the profit of the next three steps down the balance curve. Everything past the third marker is cancelled.
To price a settlement, take the balance after your last paid installment, then add the profit figures for the next three months off the same schedule. Balance plus three months of profit, plus any recorded third-party costs, is the settlement amount. The calculator linked in this guide rebuilds that schedule from your loan amount, rate and term. If your bank statement shows a different balance, enter it there: the tool uses your figure for the total and the schedule for the fee.
A worked example with SAMA's own numbers
SAMA's Financial Consumer Protection Principles and Rules print a full example for personal financing: SAR 50,000 over 12 monthly installments of SAR 4,244, settled after 6 payments. These are the regulator's published figures.
| Outstanding balance after 6 payments | SAR 25,212.74 |
| Profit, month 7 | SAR 71.62 |
| Profit, month 8 | SAR 59.77 |
| Profit, month 9 | SAR 47.88 |
| Fee (3 months of profit) | SAR 179.27 |
| Early settlement amount | SAR 25,392.01 |
| Paying to term instead (6 × SAR 4,244) | SAR 25,464, so settling saves SAR 71.99 |
The saving looks small because half the loan is already gone: six months of profit remained, SAR 251.26 in total, and the fee took three of them. A longer loan carries far more profit ahead of it.
Figure 3: After payment, the bank issues a clearance letter confirming the liability is closed.
The same rule on a five-year loan
Take a SAR 100,000 personal loan at 6% a year over 60 months, an installment of SAR 1,933. This is an example with round numbers, computed on the declining balance method. After 24 payments the balance stands at SAR 63,549, and the profit left in the remaining 36 installments totals SAR 6,049. The fee is the profit of months 25, 26 and 27: SAR 929. Settling costs SAR 64,478 today against SAR 69,598 of remaining installments, a saving of SAR 5,120. The fee consumed about 15% of the remaining profit; in SAMA's short example it consumed 71%. Earlier settlement means a smaller fee share of the profit it cancels.
With three or fewer installments left, the saving is zero
Follow the same arithmetic to the end of a loan. With three installments remaining, the fee equals the profit of those three months, which is all the profit left. The saving is exactly zero, and any third-party cost pushes settling above the cost of finishing the schedule. Settling in the final months still closes the account and ends the monthly deduction. Price it as convenience. The wide gap between fee and saving sits in the first half of the term, widest in the first year or two of a long loan.
Mortgages: check the contract date first
Article 84 carries one exception. A real estate finance agreement may prohibit early payment for up to two years from the contract date. Saudi mortgage providers disclose the practice directly: SHL Finance states in its published prices that on early settlement, the profit of the first three months is payable after two years have passed from the start of the contract, meaning months 25, 26 and 27. A home loan inside its first two years may be locked. Past that point it prices like the personal finance examples above: balance, plus three months of profit on the declining balance, plus any recorded unrecoverable third-party costs.
Settling step by step
- Request your detailed amortization schedule from the bank. SAMA's conduct rules make it free of charge, within one business day, early payment figures included.
- Run the same numbers in the settlement calculator so you hold an independent figure.
- Ask for the settlement quote itself. The lender must notify you of the early payment fees in writing within 10 business days.
- Compare the quote against the schedule: balance, three months of profit, and any third-party cost, which must be recorded in your financing file to be charged.
- Pay, then collect the clearance letter confirming the liability is settled.
Rules and figures here are as published in the SAMA Rulebook and checked in October 2026. Your contract carries the exact fee for your loan, and SAMA can amend its regulations, so confirm the number in the contract and the bank's written quote before paying. This guide covers consumer finance for individuals; business financing follows its own agreements.
FAQ
Is the Saudi early settlement fee 1% of the loan?
The 1% cap covers administrative fees charged when a contract starts: 1% of the financing amount or SAR 5,000, whichever is less (Article 83). Early payment compensation is capped at the term cost of the three months following payment, on the declining balance (Article 84).
Can I settle part of the loan instead of all of it?
Yes. SAMA's rules require the lender to accept a prepayment equal to one full installment or a multiple of it. Prepaid principal stops attracting profit from that point, because profit is charged on the outstanding balance. Ask the bank to confirm in the updated schedule how the prepayment changes your remaining term and installment.
My bank's quote is higher than the cap. What can I do?
Put your schedule next to the quote and ask the bank, in writing, to itemize any amount above the balance and three months of term cost. Third-party costs are chargeable only where they are unrecoverable and recorded in your financing file. If the written answer still exceeds the regulation, the complaint route runs first to the bank, then to the Saudi Central Bank.
Does the calculator store my loan details?
No. The Cubbbix settlement calculator runs entirely in your browser. The amounts you type never leave your device.

Was this article helpful?
Comments
Loading comments...